Roof insurance claims in Oklahoma
A roof claim brings its own numbers and terms. Understand the difference between roofing work and insurance payment, and request an inspection for the physical roof concern.
An insurance check and a roofing price are different numbers
The roofing price describes the work. An insurance payment describes what the policy pays for a covered loss. A deductible, depreciation, excluded work or an upgrade can leave a difference between the two.
The Oklahoma Insurance Department distinguishes actual cash value from replacement-cost coverage. A roof can also have terms different from the rest of the house. The example below explains the payment sequence without predicting your coverage.
Three numbers explain the payment gap
Simplified illustration only. Limits, exclusions, settlement terms, mortgage interests and actual project costs can change a claim.
From roof damage to a claim decision
Protect and preserve the evidence
Keep people away from danger, document visible damage safely and retain temporary-protection receipts. Do not climb onto a damaged roof.
Establish the roof condition
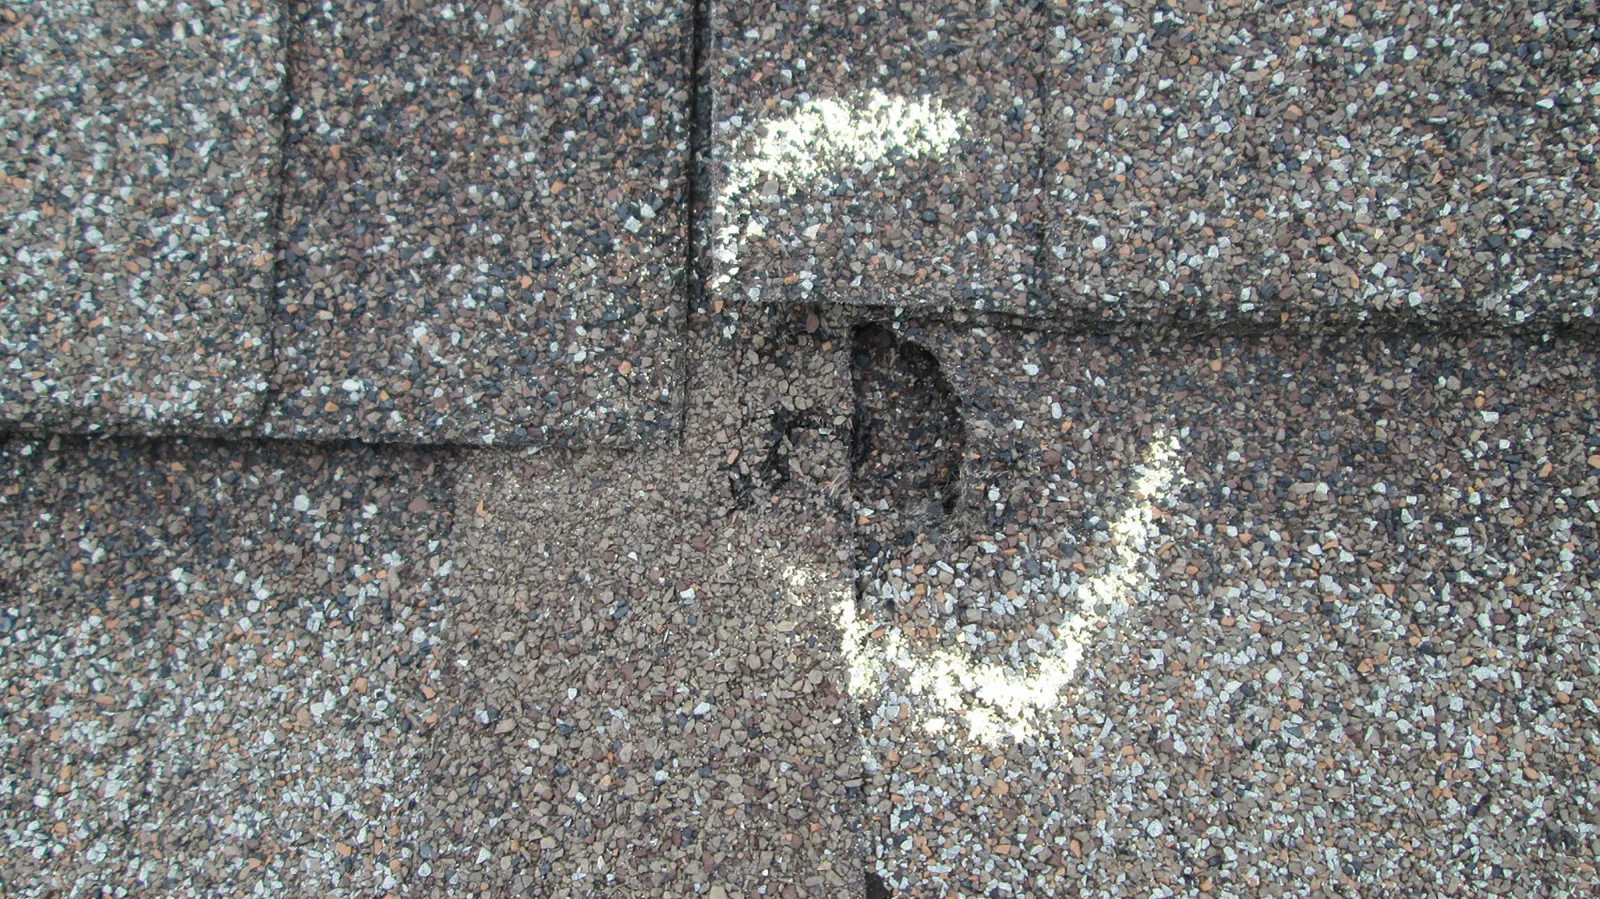
A roofer looks at the damage and the work needed. The findings inform the roofing discussion; they do not guarantee coverage or establish an exact damage date.
Apply the policy
The insurer handles the coverage decision, deductible and payment conditions. Approved roofing work and any chosen upgrades need to remain understandable as separate amounts.
Policy terms control the result
The Oklahoma Insurance Department’s roof-claim FAQ explains that actual cash value subtracts depreciation, while replacement-cost policies can pay an additional amount after their conditions are met.
A percentage deductible is based on the policy’s defined amount, not automatically on the roof repair price. Roof endorsements, age schedules, cosmetic-damage provisions and filing deadlines can also change the result. The policy and insurer provide those answers.
Roofing inspection is not claim representation. This site does not negotiate coverage, promise an approval or offer to waive a deductible.
Roof claim questions
Does an old roof automatically qualify for an insurance replacement?
No. Age or wear by itself is not proof of an insured loss. Coverage depends on the cause, policy and actual condition.
Why is the first check smaller than the roof estimate?
The deductible and withheld depreciation are common reasons, but exclusions, limits or differences in the approved work can also matter. The claim statement explains the insurer’s calculation.
Will insurance pay for a better shingle?
An elective upgrade can be an owner cost unless coverage or another applicable provision addresses it. Keep the base work and the upgrade distinct in the roofing conversation.